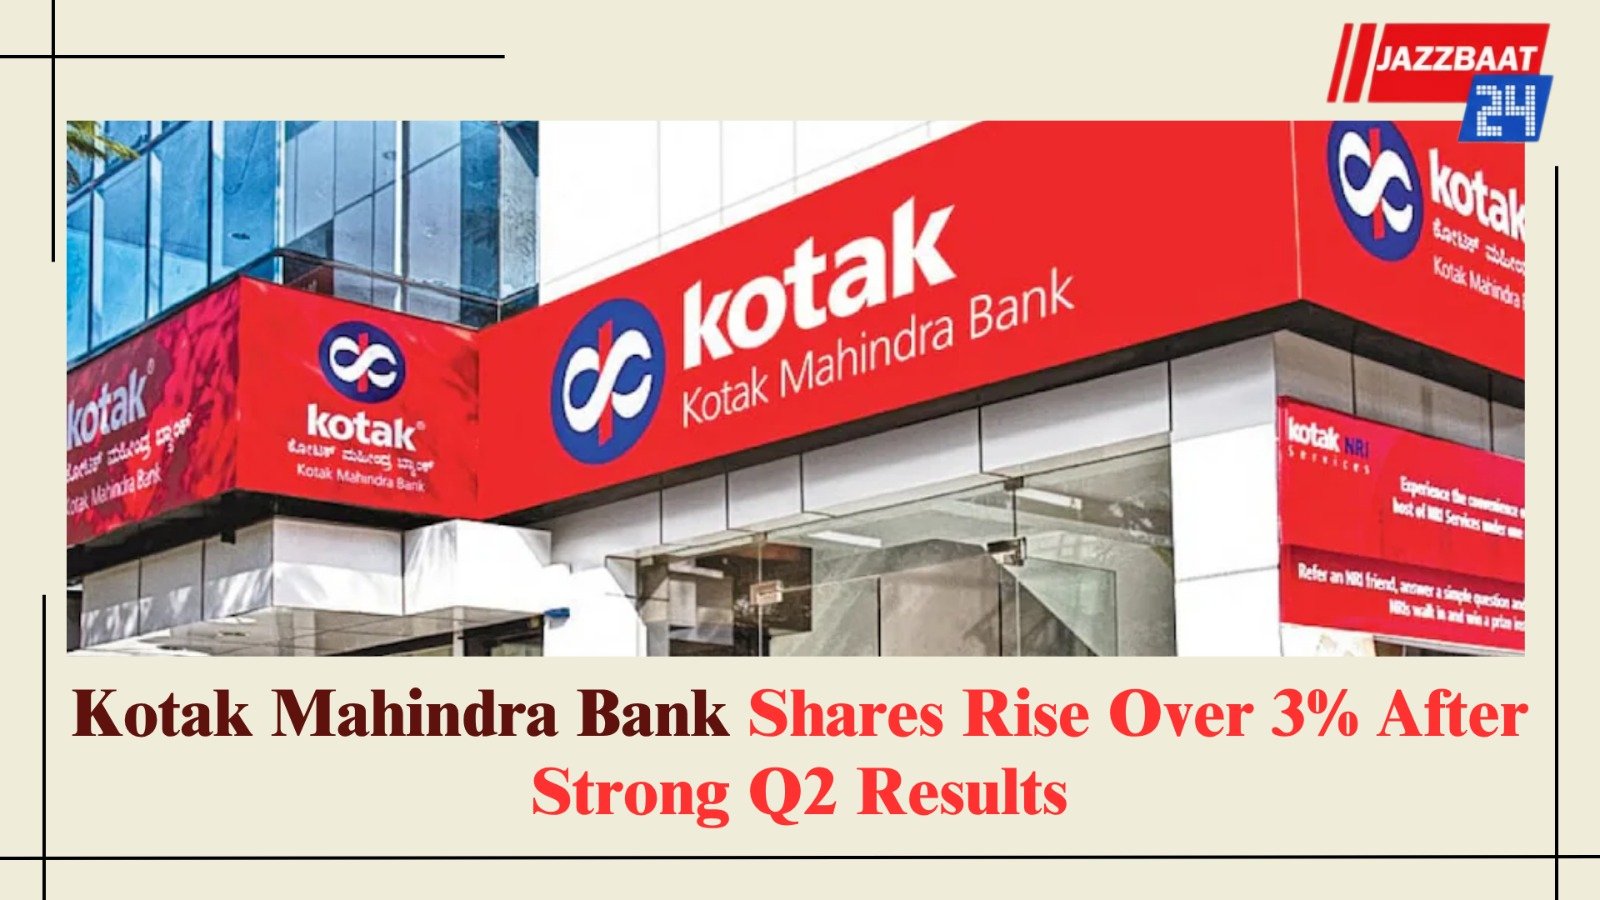
News Desk: Shares of Kotak Mahindra Bank climbed more than 3% on Monday after the private sector lender reported better-than-expected financial results for the second quarter of FY27. The bank’s strong profit growth, healthy loan expansion and improving asset quality attracted investor attention, while several brokerages maintained a positive outlook on the stock.
The share price rose as much as 3.73% to ₹446.15 on the BSE during the trading session. At around 10 am, the stock was trading 2.38% higher at ₹440.35.
Kotak Mahindra Bank reported a 29.5% year-on-year increase in net profit to ₹4,212 crore for the July-September quarter. Net interest income (NII), which measures the difference between interest earned and interest paid, increased 15.7% to ₹8,459 crore.
However, the bank’s net interest margin (NIM) declined to 4.31%, compared with 4.54% in the corresponding quarter last year. The margin pressure remains an important factor for investors to watch as the bank works to sustain earnings growth.
What Brokerages Are Saying
JPMorgan maintained its Overweight rating on Kotak Mahindra Bank and raised its target price to ₹492 per share from ₹468. The brokerage said the latest results reflected broad-based growth across key customer segments, supported by technology investments and cost discipline.
JPMorgan also expects the bank to deliver a compound annual growth rate (CAGR) of around 20% in earnings between FY26 and FY29. It believes the bank could benefit from an improvement in investor confidence as the sustainability of its earnings growth becomes clearer.
Bernstein, meanwhile, maintained its Market-Perform rating but set a target price of ₹500 per share. It highlighted healthy balance-sheet growth and loan expansion, particularly in the corporate and small and medium enterprise (SME) segments. However, it cautioned that the bank’s margin compression was sharper than that of some peers.
JM Financial upgraded its rating to Buy from Add and raised its target price to ₹500 from ₹415. The brokerage cited the bank’s healthy credit quality, available liquidity and potential for loan growth. It also expects margins to remain under pressure in the near term before recovering from the fourth quarter of FY27.
Should Investors Consider the Stock?
Kotak Mahindra Bank’s latest results have strengthened the case for monitoring its earnings growth, loan expansion and asset quality. However, the decline in net interest margin and the possibility of continued short-term pressure remain important risks.
Investors should consider their investment horizon, risk tolerance and the bank’s valuation before making a decision. Brokerage target prices are estimates, not guarantees of future returns.
Disclaimer: This article is for informational purposes only and is not investment advice. Consult a qualified financial adviser before making investment decisions.
Reader Comments 0